

Félix Pago
by Félix Pago
4.5
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.5
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
Sending money from the United States can be simple in theory and surprisingly awkward in daily life. The right choice depends less on having the longest feature list and more on whether a service fits the way you actually send money: occasionally or often, to one person or several, from a bank account or another source, and with a need for speed or a broader set of financial tools. I approached Félix Pago with that practical question in mind. It is a free finance app from Félix Pago, aimed at making transfers from the United States feel less complicated than using a traditional bank or a general-purpose financial platform.
My first impression is that its appeal comes from focus. This is not an app I would choose because it tries to be a complete banking replacement. I would consider it when the main task is sending money and I want the process to stay centered on that task. That distinction matters: a focused transfer app can feel much easier than a large banking application, but it may not satisfy someone looking for budgeting, investing, bill management, or a full account ecosystem.
How I would decide whether Félix Pago fits
Before choosing any money-transfer app, I would start with the recipient and the destination rather than the interface. A clean screen is useful, but it does not compensate for a transfer route that does not suit the person receiving the money. I would also consider how frequently I send funds, whether I need a record of repeated transfers, and how much I value a dedicated sending experience over the convenience of staying inside my existing bank.
Félix Pago is listed as a finance app with an Everyone age rating, so it is positioned as an everyday financial tool rather than a specialist service for a narrow professional audience. It is free to install, which removes an initial barrier for someone who wants to test the workflow. That does not mean every possible transfer-related cost is automatically eliminated; I would still read the amount, exchange details, and final confirmation carefully before approving a transaction.
The app has a 4.5 average from around 1.6 thousand ratings, and it has passed the threshold of 100 thousand installs. Those figures suggest that the experience has attracted meaningful use, but I would not treat popularity as a substitute for checking whether the recipient’s situation matches the service. A transfer app can be well liked and still be the wrong tool for a particular destination, frequency, or funding method.
One useful decision rule is to separate “sending money” from “managing money.” If I only need to move funds from the United States, a dedicated app may reduce the number of steps and distractions. If I want to hold balances, monitor spending, automate savings, or manage several financial products in one place, I would begin with my bank or a broader financial app instead. Félix Pago makes more sense when the transfer itself is the center of the job.
The everyday situation where it makes the most sense
Imagine that I need to send money to a family member while I am away from my computer. I do not want to open a bank website, search through several menus, or wonder whether I selected the right international option. A focused app can be valuable in that moment because it keeps the task narrow: open the service, enter the transfer details, review the information, and finish the request. The benefit is not merely speed. It is reduced mental effort when I am already busy.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I would also see a use case for someone who sends support regularly but not frequently enough to justify a complicated personal finance setup. In that situation, the best workflow is to treat each transfer as a deliberate checkpoint. I would verify the recipient before confirming, keep the confirmation information, and avoid rushing simply because the interface feels easy. Convenience should shorten navigation, not replace financial care.
A less obvious benefit of a focused transfer app is that it can make responsibilities clearer. When a general banking application combines cards, deposits, loans, alerts, and transfers on the same screen, it is easy to lose sight of the exact transaction being made. A service built around sending money may help me concentrate on the amount and recipient. That is a small design advantage, but it becomes meaningful when I am sending money on a phone in a noisy or distracting environment.
What I would check before the first real transfer
I would not begin with a large amount. My preferred approach would be a small, planned test to confirm that the recipient details and delivery route work as expected. This is especially sensible when sending to someone for the first time. Once that process is familiar, later transfers can be quicker without becoming automatic or careless.
I would also prepare the recipient’s information before opening the app. Copying details from a trusted source reduces the chance of typing errors, and reviewing the final screen slowly is more valuable than saving a few seconds. A practical habit is to compare the recipient information character by character and then check the amount again after any conversion or adjustment shown during the process.
Another useful habit is keeping a simple personal note after sending. I would record the date, amount, recipient, and purpose outside the app if I need to reconcile family support or recurring obligations. This is not a criticism of Félix Pago; it is a sensible separation between a transfer tool and a personal record-keeping system. A sending app can complete the transaction without being the best place to organize a long-term household budget.
Where the focused approach wins, and where another option may fit
The strongest case for Félix Pago is simplicity of purpose. Instead of asking me to learn a large financial platform, it presents itself as a direct way to send money from the United States. For a person who finds traditional international-transfer menus intimidating, that focus can make the first step less stressful. It is also a practical choice for someone who wants a separate sending workflow rather than mixing transfers with everyday card spending.
Compared with a traditional bank, the likely advantage is a more concentrated experience. Banks are useful when I want everything connected to an existing account, but their transfer sections can be surrounded by terminology and settings that are irrelevant to a one-off payment. I would choose the bank when account history, established support channels, or keeping all activity in one statement matters more than a specialized interface.
Compared with a broad digital wallet, Félix Pago may appeal to someone who does not want to build another general-purpose financial account. Wallets can be convenient for people who already use them for purchases and peer-to-peer payments. However, if my recipient or my own routine is already tied to a particular wallet, switching to a separate service may introduce an extra step instead of removing one. The best choice is the one that reduces friction for both sides, not only for the sender.
Compared with cash-based alternatives, an app can offer a more organized digital process, but it also requires comfort with entering financial information on a phone and following an electronic confirmation flow. Someone who has unreliable access to a smartphone, prefers in-person assistance, or needs a method built around cash collection may be better served elsewhere. I would not recommend a mobile transfer app simply because it is modern; the recipient’s access and confidence matter just as much.
There is also a trade-off between specialization and flexibility. Félix Pago is easier to understand when the goal is sending money, but a specialized service may not replace the wider controls found in a bank or full financial platform. If I send money only once every few months, the focused design may still be worthwhile. If I am trying to manage an entire household’s finances, I would probably use it alongside another tool rather than expecting it to do everything.
Questions I would answer before switching
Does free mean the whole transaction costs nothing? I would not assume that. The app itself is free, but transfer services can present costs through the transaction flow, exchange details, or the receiving route. Before confirming, I would inspect the amount being sent, the amount expected by the recipient, and any information shown in the review step. The important comparison is the final result, not just the absence of an installation charge.
Is it suitable for occasional users? Yes, that is one of the situations where I can see its focused design helping. Occasional users do not necessarily need a complex financial platform, and a dedicated transfer app can be easier to revisit when the task arises. I would still keep my recipient information organized because an app cannot prevent mistakes caused by outdated contact details.
Should I use it for recurring support? It can be considered for that routine, but I would keep a separate schedule and record rather than relying on memory. Recurring transfers need more than a smooth first experience: I would want a repeatable checklist, a reminder system, and a habit of reviewing the recipient and amount each time. The app can be the sending step without becoming the entire system for managing the obligation.
What if I already use my bank or a wallet? I would compare the complete workflow. If the existing option is already easy for the recipient, clearly displays the final amount, and keeps useful records, changing may not improve anything. Félix Pago becomes more compelling when my current method feels confusing, takes too many screens, or is not designed around the kind of transfer I make. Switching for a different logo is not a good reason; reducing repeated friction is.
Will it suit someone who needs broader financial tools? I would look elsewhere first. The app’s identity is centered on sending money from the United States, so I would not choose it as my main solution for budgeting, investing, credit management, or everyday banking. It may work well as one part of a financial routine, but people seeking a single app for every money task should compare it with a broader platform.
The real cost of changing a transfer routine
Switching apps is not only about downloading a new icon. I would need to learn the flow, confirm how recipient information is entered, understand what appears before approval, and decide where to keep confirmations. That learning curve may be short for a focused service, but it still exists. The first transfer should be treated as setup rather than as a race.
There is also a social cost when the recipient is accustomed to another method. If the person receiving the money has a reliable routine already, asking them to adapt can create more inconvenience than the sender saves. I would discuss the change in advance, especially for recurring support. A transfer method is successful only when the money reaches the intended person in a way they can use comfortably.
For that reason, I would test Félix Pago in parallel with the current method instead of abandoning the old routine immediately. I would compare clarity, confirmation, recipient experience, and the final amount across a small transaction. This side-by-side test is more useful than judging the app after installation alone. It also gives me a practical fallback if the new process does not suit a particular recipient.
The current version is 1.1.14, and the app supports Android 7.0 or later. That makes checking the phone’s operating-system compatibility a sensible first step before planning a switch. I would also keep the app updated through the official app store, particularly for a finance tool, because staying current is a basic part of maintaining a reliable mobile workflow.
My recommendation after weighing the trade-offs
I recommend Félix Pago to people whose main need is sending money from the United States and who want a dedicated, less distracting experience. Its free entry point, finance-focused purpose, and straightforward positioning make it worth trying for occasional senders, family-support situations, and anyone frustrated by overly broad banking interfaces. I especially like the idea of using it as a deliberate transfer tool while keeping budgeting and record-keeping in a separate system.
I would not recommend switching automatically if a bank or wallet already handles the same transfers clearly and conveniently. Nor would I make it my first choice for someone seeking a complete financial home. The app’s strength is concentration, and concentration is only an advantage when the task is narrow enough to benefit from it.
My practical advice is to install it, confirm that the phone meets the Android requirement, review the recipient workflow, and begin with a small test. Pay attention to the final transaction details rather than judging the service only by its free download. If the process feels easier for both sender and recipient, Félix Pago can earn a permanent place in the routine. If it adds another account, another record to maintain, or another step for the recipient, the familiar alternative may remain the better choice.
Overall, I see Félix Pago as a focused option rather than a universal answer. That is a positive distinction, not a weakness: it knows the problem it is trying to solve. For the right sender, its value lies in making a money transfer feel like one clear task instead of a tour through a full banking system. For everyone else, the smartest decision is to compare the complete experience and choose the method that remains understandable from the first tap to the recipient’s final confirmation.
Pros
- Simple way to send money internationally through a mobile app.
- Supports transfers to several Latin American countries.
- Recipients may receive funds directly in local currency.
- Clear transfer tracking helps monitor payment progress.
- Useful for users without access to traditional banking services.
Cons
- Availability and supported corridors vary by country.
- Exchange rates and fees can change between transactions.
- Identity verification may be required before sending money.
- Transfer times can depend on weekends, banks, and local providers.
- Customer support response times may vary during busy periods.
FAQs for Félix Pago
What is Félix Pago and how does it work?
Félix Pago is a digital remittance service designed to help users send money internationally through a simple chat-based experience. Depending on the sender’s location and the supported destination, you can typically start a transfer by messaging Félix, providing recipient and payment details, and confirming the transaction. Availability, delivery methods, exchange rates, and supported countries may vary, so review the current terms before sending money.
Is Félix Pago safe to use for international money transfers?
Félix Pago uses account verification and transaction-security measures intended to protect users and reduce fraud. However, no financial service is completely risk-free. Before using it, download the app only from an official store, check that the developer information is correct, enable available security features, and never share passwords, verification codes, or payment details with anyone claiming to represent Félix outside official support channels.
What information do I need to send money with Félix Pago?
The exact requirements depend on your country, transfer amount, payment method, and recipient destination. You may be asked for your legal name, phone number, identity information, a valid payment method, and the recipient’s full details. Larger or unusual transfers can require additional verification. Make sure all names and account information are accurate because incorrect recipient details may delay delivery or complicate cancellation.
How much does Félix Pago charge, and what exchange rate is used?
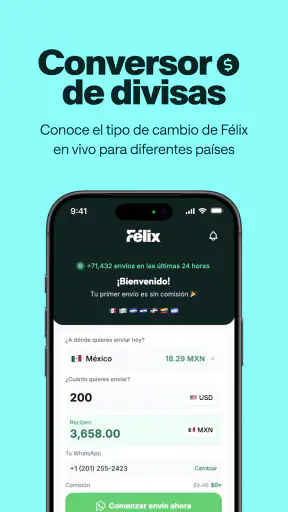
Transfer costs and exchange rates can differ according to the sending country, destination, payment method, delivery option, and amount. Félix Pago should normally display the applicable fee, exchange rate, and final amount before you confirm a transaction. Check this summary carefully rather than relying on an advertised starting price, since the recipient’s received amount may change when fees or currency conversion are applied.
How long do Félix Pago transfers take, and can they be canceled?
Delivery time depends on the destination, recipient payout method, banking or mobile-wallet processing, weekends, holidays, and any required compliance review. Some transfers may arrive quickly, while others can take longer. Cancellation is not guaranteed once a transfer has been processed or collected. If you notice an error, contact official Félix Pago support immediately and keep your transaction reference available.

Félix Pago
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via marketing@felixpago.com, visit https://www.felixpago.com/, or review their https://www.felixpago.com/legal/politicas-de-privacidad.










